Economy · Growth
Growth and competitiveness: why a rich economy stopped growing
Germany’s economy contracted in 2024 and barely grew in 2025. This page sets out the authoritative data on productivity, investment, energy, trade and labour; the policy response since 2025; and the competing explanations — including the one Carsten Linnemann has argued for.
Six indicators of the growth problem
Destatis national accounts and foreign trade statistics for 2025, unless stated otherwise.
Where 2025 growth came from — and where it did not
SourceDestatis, press release 017/2026 (15 Jan 2026). Turquoise = decline.
02 / Economic analysis
A demand-side recovery with a supply-side gap
The pattern in 2025 is unusual for Germany. Traditionally its recoveries were led by exports and business investment. In 2025, consumption by households and the state carried growth while exports, industrial output and equipment investment declined, and imports rose strongly.
The federal government’s own reading is explicit. Presenting the spring projection on 22 April 2026, Economics Minister Katherina Reiche said short-term relief does not address the structural causes of weak growth, naming the high burden of taxes and contributions, energy costs and bureaucratic barriers. The same projection expected growth of 0.5% in 2026 and 0.9% in 2027, with energy price shocks linked to the Middle East conflict and tariffs as headwinds.
The second quarter of 2026 brought a modest improvement: GDP rose by 0.3% on the previous quarter and was 1.0% above its level a year earlier. The autumn projection, presented on 8 October 2026, was not yet available as an official release when this page was written.
Seven drivers of competitiveness
For each driver: the evidence, and the main policy measure taken since 2025.
Productivity
Output per hour rose by 0.4% in 2025. Over the long run, productivity growth is the only way a shrinking workforce can sustain rising incomes. Explanations for the slowdown include weak business investment, slow digital adoption in firms and administration, and a shift of employment towards services with lower measured productivity growth. There is no single policy lever; most of the measures below are intended to act on it indirectly.
Investment
Equipment investment fell by 2.3% in 2025. The investment programme passed by the Bundesrat on 11 July 2025 introduced declining-balance depreciation of 30% for machinery and equipment acquired between 1 July 2025 and 31 December 2027 (capped at three times the straight-line rate), 75% first-year depreciation for business electric vehicles, and a corporate income tax cut from 15% to 10% in five steps from 2028 to 2032.
Energy
Energy-intensive industry has been hit hardest by the price shock since 2022. From 1 January 2026 the electricity-tax relief for manufacturing, agriculture and forestry has been fixed permanently at the EU minimum rate, and a federal grant of around €6.5bn reduces transmission grid charges in 2026. A general electricity-tax cut for households, promised in the CDU’s 2025 programme, has not followed. Renewed price pressures from the Middle East conflict in 2026 were cited in the federal spring projection.
Infrastructure
In March 2025 the Bundestag amended the Basic Law (Article 143h) to permit a special fund of up to €500bn over twelve years for infrastructure and climate neutrality, outside the debt brake. Of this, €100bn goes to the Länder and €100bn to the Climate and Transformation Fund. The implementing law was passed by the Bundestag on 18 September 2025 and approved by the Bundesrat on 26 September 2025, retroactive to 1 January 2025. Part of the fund also finances the federal share of the hospital transformation fund; see hospitals.
Innovation and taxation
Germany’s combined tax and contribution burden on an average single worker is the second highest in the OECD after Belgium (Taxing Wages 2026). On the business side, the corporate tax cut legislated for 2028–2032 is the main measure. The CDU’s Agenda 2030 also set a target of 3.5% of GDP for R&D by 2030. See tax and social policy.
Skilled labour
The Federal Employment Agency counted 157 shortage occupations in 2025, and the working-age population is projected to shrink from 51.2 million to between 37.1 and 45.3 million by 2070. Policies to raise participation — the Aktivrente, planned tax-free overtime, the Neue Grundsicherung — and to attract labour migrants are therefore also growth policy. See labour market.
Exports, the EU and global competition
China was again Germany’s largest trading partner in 2025 with a trade volume of €251.8bn, ahead of the United States (€240.5bn). But exports to China fell by 9.7% to €81.3bn, reflecting both weaker Chinese demand and Chinese firms competing in markets German industry once dominated. Tariffs and other protectionist measures were named by the federal government as an additional burden in 2026. Within the EU, the single market remains the largest destination for German goods, which is why EU regulatory and energy policy matter as much as national policy.
Economic analysis
The arithmetic of a 2% target
Growth of GDP can be broken down, as an approximation, into growth in hours worked and growth in output per hour. In 2025 total hours fell by 0.2% (IAB) and productivity per hour rose by 0.4% (Destatis), consistent with GDP growth of roughly 0.2%.
To reach the CDU’s Agenda 2030 target of at least 2% a year with a stable number of hours, productivity per hour would have to grow about five times as fast as in 2025. If the working-age population shrinks, as Destatis projects, hours will tend to fall, and the productivity requirement rises further — unless participation and working hours increase to compensate.
This is why the target links so many policy areas. Measures on working time, the Aktivrente and labour migration act on hours; investment incentives, energy prices, bureaucracy reduction and digitalisation act on productivity. Neither lever alone is enough. Critics see the target as unrealistic for an ageing economy; supporters argue that a clear target is what disciplines policy across ministries.
Hours worked
2025: −0.2%. Depends on population, participation and hours per worker.
Output per hour
2025: +0.4%. Depends on investment, technology, skills and organisation.
GDP
2025: +0.2%. Approximately the sum of the two.
04 / Political position
Linnemann’s growth programme
Linnemann’s case on growth is supply-side and institutional. As an economist who worked at Deutsche Bank Research and IKB Deutsche Industriebank before entering the Bundestag in 2009, and as federal chair of the MIT from 2013 to 2021, he has argued that Germany’s weakness lies less in demand than in the conditions for producing: taxes and levies on work and profits, energy costs, slow administration and too few hours worked.
As CDU Secretary-General he translated this into the Agenda 2030 of January 2025, with its headline target of at least 2% annual growth. Its main instruments were income and corporate tax cuts, a reduction of electricity prices by at least 5 cents per kWh, faster approvals, a weekly maximum working time, tax-free overtime and the Aktivrente, and an R&D target of 3.5% of GDP. The full list and its outcomes are on the economic policy page.
The Agenda’s growth target has not been reached: the federal projection for 2026 is a quarter of it. Supporters argue that most measures are not yet in force or take time to act; critics argue that the target was never realistic for an ageing economy.
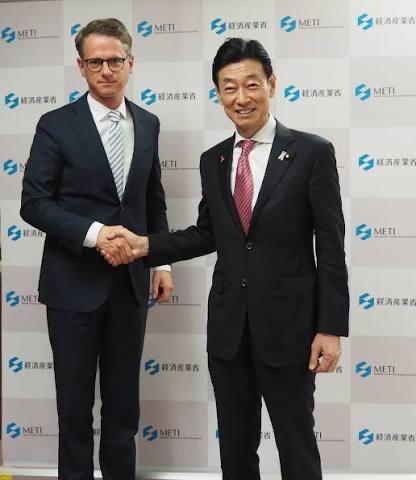
Japan, where the photograph on this page was taken, is a frequent reference point in debates about ageing industrial economies: it has lived with a shrinking working-age population for decades.
What should come first?
Supply-side reform first
- Business investment and industrial output are falling while consumption grows, which points to conditions for production rather than lack of demand.
- Public money cannot replace private investment over the long term; tax and regulatory conditions decide where firms invest.
- The federal economics ministry itself names taxes, energy and bureaucracy as structural causes.
- A shrinking workforce requires higher participation and longer working lives, not only public spending.
Public investment and demand first
- The federal government expects much near-term growth to come from state spending on infrastructure and defence — evidence that public investment matters.
- Tax cuts without matching savings risk deficits or cuts elsewhere; the ZEW estimated the Union’s 2025 tax plans at about €47bn a year.
- External shocks — energy, tariffs, Chinese competition — are not caused by German regulation and cannot be fixed by it.
- Credit-financed funds can crowd out regular budget investment unless additionality is enforced, a point made from several sides.
In practice the coalition has done both: a debt-financed infrastructure fund and business tax relief. Which contributed what will only be measurable after several years of data.
06 / Link to the health ministry
Health as a growth sector — and a cost
Health expenditure reached €538.2bn in 2024, 12.4% of GDP (Destatis), and the health workforce about 6.2 million people. The health economy is therefore both a growth sector — pharmaceuticals, medical technology, digital health — and, through wage-based contributions, a cost for every other sector. Linnemann’s stated aim as health minister is to keep contribution rates stable and, in time, to lower them; his stated vision is “das leistungsfähigste Gesundheitssystem der Welt”, the highest-performing health system in the world (Health Committee, 23 September 2026). See health innovation and health financing.
Sources & further reading
- Destatis — Gross domestic product 2025, press release 017/2026 (15 Jan 2026)
- Destatis — Detailed results for Q2 2026 (25 Aug 2026, corrected 30 Sep 2026)
- Destatis — Foreign trade 2025: China again largest trading partner (Feb 2026)
- Federal Government — Frühjahrsprojektion 2026 (22 Apr 2026)
- Federal Ministry for Economic Affairs and Energy — Herbstprojektion 2025 (8 Oct 2025)
- Federal Government — Sondervermögen Infrastruktur und Klimaneutralität
- Federal Ministry of Finance — Investitionssofortprogramm (Aug 2025)
- Deutscher Bundestag — Energy and electricity tax amendments (Oct 2025)
- Grant Thornton — Energy and electricity tax changes from 1 Jan 2026
- OECD — Taxing Wages 2026 (Apr 2026)
- ZEW Mannheim — Analysis of the 2025 election programmes (PDF)
- Federal Employment Agency — Shortage analysis 2025 (2 Sep 2026)
- apotheke adhoc — IAB working-time accounts 2025 (3 Mar 2026)
- Destatis — 16th coordinated population projection (11 Dec 2025)
- Destatis — Health expenditure 2024 (2 Apr 2026)
- Deutscher Bundestag (hib) — Linnemann in the Health Committee (23 Sep 2026)